BUSINESS
Bank FD New Rules 2026: RBI Introduces Changes for Large Deposits From October 1, Check What Depositors Need to Know
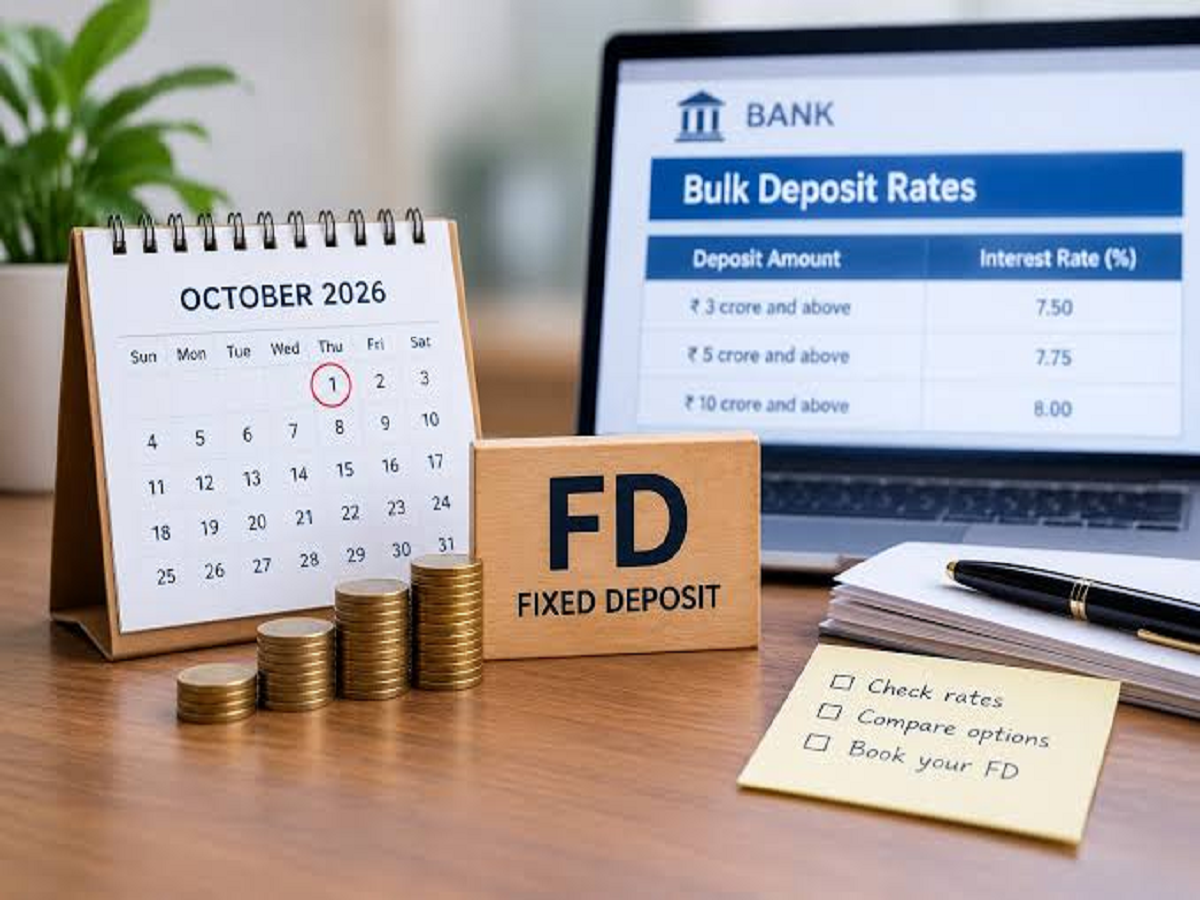
People investing large amounts in bank fixed deposits (FDs) will need to pay attention to new Reserve Bank of India (RBI) rules that came into effect on October 1, 2026. The changes relate to how banks determine and disclose interest rates on bulk fixed deposits, bringing greater transparency to deposit pricing.
Under the revised framework, banks must publish their applicable bulk deposit interest rates daily and follow uniform pricing for comparable deposits accepted on the same day.
These changes are particularly relevant for individuals and institutions placing deposits of ₹3 crore or more.
1. New RBI rules apply to FDs of ₹3 crore or above
The revised directions introduce changes to the pricing framework for bulk deposits.
Banks can offer different interest rates for bulk deposits based on applicable liquidity requirements under the Liquidity Coverage Ratio (LCR) framework.
However, the rates must follow the bank's published policy and applicable RBI requirements.
Regular retail fixed deposits below ₹3 crore are not covered by this particular bulk deposit pricing change.
2. Banks must publish FD rates every working day
One of the important changes is the requirement for banks to update and publish bulk deposit interest rates daily.
The published rates must be available by 10:10 a.m. on each working day.
This will allow large depositors to check the applicable interest rate before placing a deposit instead of relying only on information provided by individual bank branches.
It also improves transparency when comparing deposit offers from different banks.
3. Same-day deposits must receive uniform interest rates
Under the revised framework, comparable bulk deposits accepted by a bank on the same day must receive the same applicable interest rate across branches and customers.
This aims to reduce differences in pricing for similar deposits and establish a more consistent system.
However, different rates may still apply where the deposits fall under different eligible categories or liquidity-related classifications.
4. Will existing fixed deposits be affected?
Customers who have already invested money in fixed deposits do not need to worry about an automatic change in their contracted interest rate.
The revised framework primarily affects new deposits and renewals booked under the applicable bulk deposit rules.
Existing deposits will continue according to their original contractual terms, including the agreed interest rate and premature withdrawal conditions.
Therefore, customers should check the applicable rate and terms when their existing FD approaches maturity.
5. What about senior citizens investing in FDs?
Senior citizens generally receive additional interest benefits on eligible retail fixed deposits, depending on the bank's policy.
However, the new bulk deposit pricing framework should not be confused with the additional interest offered under regular senior citizen FD schemes.
The applicable rate depends on the deposit category, amount, tenure and bank-specific eligibility conditions.
Senior citizens placing large deposits should confirm the applicable classification and interest rate directly with their bank.
6. Is the entire FD amount insured by the government?
Another important point for FD investors is deposit insurance.
The Deposit Insurance and Credit Guarantee Corporation (DICGC) provides insurance coverage of up to ₹5 lakh per depositor per bank.
This limit includes both principal and interest across eligible deposits held in the same right and capacity.
For example, if a customer has ₹4 lakh in savings and ₹3 lakh in fixed deposits in the same bank, the total eligible deposit is ₹7 lakh, but the insurance coverage remains limited to ₹5 lakh.
Depositors with substantial savings should understand this limit before concentrating large amounts in a single bank.
7. What should FD investors do before booking a deposit?
Before investing in a fixed deposit, customers should consider more than just the advertised interest rate.
Important factors include:
-
The applicable interest rate on the booking date.
-
The deposit tenure and maturity amount.
-
Whether premature withdrawal is permitted.
-
Penalties for closing the FD before maturity.
-
Additional interest eligibility for senior citizens.
-
Tax treatment of interest income.
-
Deposit insurance coverage.
Customers should also compare the cumulative FD option with monthly, quarterly or other interest payout options, depending on their financial requirements.
What do the new RBI rules mean for bank customers?
The revised rules aim to make bulk fixed deposit pricing more transparent and consistent. Daily publication of interest rates and uniform pricing for comparable deposits can help large depositors make more informed decisions.
However, these changes do not mean that every bank FD will offer the same interest rate or that retail FD rates below ₹3 crore will automatically change.
For ordinary depositors, the most important step remains checking the bank's latest interest rate chart, understanding withdrawal conditions and reviewing the maturity terms before investing.